Category Archives: Tax Newswire (Only used for the newswire)

Legislation gives separating couples time to avoid taxation on assets

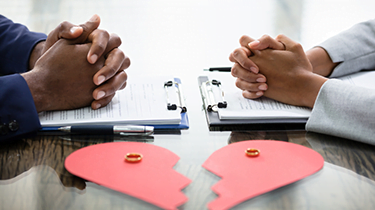
Divorcing or separating couples will have more time to get their affairs in order and avoid having to pay Capital Gains Tax (CGT) when new legislation comes into force.

Currently, if any transfer arrangements for assets are not completed within the tax year of separation, they could be subject to CGT.

Proposed new legislation dealing with the transfer of assets between partners provides that transfers of assets are made on a “no gain or no loss” basis in any tax year in which they are living together.

Exemption period extended

When spouses or civil partners separate, no gain or no loss treatment is only available in relation to any disposals in the remainder of the tax year in which the separation happens. After that, transfers are treated as normal disposals for CGT purposes.

The proposals will stretch this CGT exempt period to three years for separating couples, and allow any assets which are the subject of a divorce agreement to be transferred on a no gain/no loss basis without time limit.

This will apply for all disposals that occur on and after 6 April 2023 and has been brought about following a recommendation by the Office of Tax Simplification (OTS).

The final contents of Finance Bill 2022-23 will be subject to confirmation at Budget 2022 and are expected to confirm:

  • Separating spouses or civil partners be given up to three years after the year they cease to live together in which to make no gain or no loss transfers
  • No gain or no loss treatment will also apply to assets that separating spouses or civil partners transfer between themselves as part of a formal divorce agreement
  • A spouse or civil partner who retains an interest in the former matrimonial home be given an option to claim Private Residence Relief (PRR) when it is sold
  • Individuals who have transferred their interest in the former matrimonial home to their former partner and are entitled to receive a percentage of the proceeds when that home is eventually sold, be able to apply the same tax treatment to those proceeds when received that applied when they transferred their original interest in the home to their ex-spouse or civil partner

Preparing for Making Tax Digital and income tax

Self-employed businesses and landlords will come under the umbrella of the Government’s Making Tax Digital from 2024.

Making Tax Digital (MTD) for Income Tax Self-Assessment (ITSA) will be introduced on 6 April 2024. It was originally planned to be introduced in April next year but was delayed because the Government recognises the challenges faced by many UK businesses as the country emerges from the pandemic.

MTD is part of the Government’s plans to make it easier for individuals and businesses to get their tax right and keep on top of their affairs.

Who will be affected by the change?

Businesses with income greater than £10,000 per year from:

  • Self-employment
  • General partnerships with only individuals as partners
  • Property businesses (UK and overseas)

It will affect those with an annual business or property income above £10,000, who will need to follow the rules from that date and will replace the current system of annual Self Assessment tax returns.

Partnerships with individual partners will be required to follow the rules from April 2025.

Business owners and landlords will no longer file an annual self-assessment tax return, unless exempt from MTD for ITSA.

Instead, each business will need to file four quarterly updates and an End of Period Statement to finalise business profits. They will then need to submit a Final Return with any other income, gains or reliefs.

Who may be exempt?

You can apply if it’s not reasonable or practical for you to use computers, software or the internet if the following applies:

  • Your age, a disability or where you live
  • An objection to using computers on religious grounds
  • For any other reason why it’s not reasonable or practical

HMRC will consider each application on its merits.

A recent survey on Making Tax Digital (MTD) shows taxpayers have an alarming lack of readiness and enthusiasm for the changeover and a lack of awareness that MTD for Income Tax begins in less than two years. The survey by Ipsos showed lack of experience with MTD software was a big problem. A big majority, (86 per cent), had turnover, property income or combined turnover and property income below the VAT threshold, therefore they had no previous experience of using the software.

UK residence rules and how much tax you pay

When it comes to paying tax in the UK, your residence status will affect how much tax you pay on foreign income.

HM Revenue & Customs (HMRC) has launched a new tool to define tax residence status and applies the rules as set out in the Statutory Residence Test (SRT) to help determine an individual’s residence status for tax purposes. 

From 6 April 2013 new statutory tests were introduced to determine whether individuals are resident in the UK or not. It can be complicated and there will still be situations where someone’s tax residence isn’t clear between spending substantial time overseas and also making visits to the UK.

Non-residents only pay tax on their UK income – they do not pay UK tax on their foreign income.

Residents normally pay UK tax on all their income, whether it’s from the UK or abroad. But there are special rules for UK residents whose permanent home (‘domicile’) is abroad.

Work out your residence status

You’re automatically non-resident if either:

  • You spent fewer than 16 days in the UK (or 46 days if you have not been classed as UK resident for the 3 previous tax years)
  • You work abroad full-time (averaging at least 35 hours a week) and spent fewer than 91 days in the UK, of which no more than 30 were spent working

You may be resident under the automatic UK tests if:

  • You spent 183 or more days in the UK in the tax year
  • Your only home was in the UK and it was available to use for at least 91 days in total – and You spent time there for at least 30 days in the tax year
  • You worked full-time in the UK for any period of 365 days and at least one of these days fell into the specific tax year

You may also be resident under the sufficient ties test if you spent a number of days in the UK and you have additional links, like work or family.

You can use the residence status checker if you’re still unsure about your status. This will indicate whether you were a UK resident in any tax year from 6 April 2016.

Savers facing being taxed on interest for the first time

Rising interest rates are a worry for those with a mortgage or loan, but for savers, it means an increase on their investment as savings rates rise.

It also presents a challenge and can tip savers into the bracket where they have to start paying tax on their interest.

The latest interest rate rise in August saw a full half percentage point increase.

The rise means that more savers could have to pay tax on increased interest made from savings.

The Personal Savings Allowance (PSA) allows savers to earn up to £1,000 of interest and not have to pay tax on it, depending on their Income Tax band. This reduces to £500 at the higher rate and disappears for the additional rate.

For those with a joint account, interest will be split equally between the account holders. According to HMRC, interest on savings covers:

  • Savings and credit union accounts
  • Bank and building society accounts
  • Unit trusts, investment trusts and open-ended investment companies
  • Peer-to-peer lending
  • Trust funds
  • Payment protection insurance (PPI)
  • Government or company bonds
  • Life annuity payments
  • Some life insurance contracts

The PSA was introduced in April 2016 and means any savings earned won’t be taxed up to a certain limit based on an individual’s current income tax rate.

The downside is that in the six years since its introduction, the figure has remained at £1,000.

However, before reaching the £1,000 PSA limit, you would need tens of thousands of pounds in the savings accounts, at current interest rates. Even with some of the higher paying accounts.

A basic tax rate saver would need to have around £30k in an account paying 3.35 per cent before coming close to breaching the PSA limit. It is estimated that around 95 per cent of savers don’t pay any tax on their savings interest due to the PSA.

Need help and advice on savings and taxation matters? Please call our team today.

HMRC warns taxpayers to beware of phishing fraudsters

Cybercrime is on the rise and taxpayers have been warned to beware of fraudsters attempting to steal money and information.

The criminals are faking the role of the official bodies like HM Revenue & Customs, even copying logos and letterheads to make correspondence look official. The assumed official identities can trick their victims into handing over money or personal or financial information.

They are very clever and can change their tactics before being identified and they will communicate via email, known as phishing, SMS, phone calls or bogus websites.

HMRC warns that when someone clicks the link from the fraudster, they may be signing away their bank details, or downloading intrusive malware that spreads through their IT system.

Scams come in many forms.

  • Some threaten immediate arrest for tax evasion
  • Others offer a tax rebate
  • Some may offer financial inducements to reply

HMRC will never ask for personal or financial information when we send text messages.

Do not reply if you get a text message claiming to be from HMRC offering you a tax refund in exchange for personal or financial details. Do not open any links in the message.

Contacts like these should set alarm bells ringing, so if you are in any doubt whether the email, phone call or text is genuine, you can check the ‘HMRC scams’ advice on GOV.UK and find out how to report them to us.

So to avoid falling prey to these events, ignore – i.e. delete without opening – any email that purports to be a tax-related HMRC correspondence. Don’t click on web links, attachments or downloads. The same goes for social media messages and anything that comes through your phone.

Report any suspicious activity to HMRC

Myrtle Lloyd, HMRC’s Director General for Customer Services, said: “Never let yourself be rushed. If someone contacts you saying they’re from HMRC, wanting you to urgently transfer money or give personal information, be on your guard. HMRC will also never ring up threatening arrest. Only criminals do that.”

Potential victims can report suspicious phone calls using a form on GOV.UK. Customers can also forward suspicious emails claiming to be from HMRC to phishing@hmrc.gov.uk and texts to 60599.

There is a dedicated team working on cyber and phone crimes. They use innovative technologies to prevent misleading and malicious communications from ever reaching the customer. HMRC says that since 2017 these technical controls have prevented 500 million emails from reaching HMRC’s customers.